Bork Roofing
Roof Financing: Ways to Pay for a New Roof in Idaho
Since 2004. GAF Master Elite. Idaho RCE-6110.
Schedule a Free Roof Inspection
Idaho homeowners pay for roofs four main ways: an insurance claim when storm damage caused the problem, savings, home equity, or a payment plan through a lender the roofing contractor works with. Each path has trade-offs. Compare them before you sign anything, and ask Bork Roofing about payment options at your estimate.
Idaho homeowners pay for roofs four main ways: an insurance claim when storm damage caused the problem, savings, home equity, or a payment plan through a lender the roofing contractor works with. Each path has trade-offs. Compare them before you sign anything, and ask Bork Roofing about payment options at your estimate.
A roof is one of the bigger checks most homeowners ever write, and the cost guide shows why the number swings so much. The good news: you have more ways to pay than the one a salesperson happens to pitch. One route that closed is the federal energy credit for roofing. This page walks through each of them in plain words, with no lender names and no rate promises, so you can pick with clear eyes.
Question
How do people pay for a new roof?
Four ways cover nearly every roof replacement in the valley: an insurance claim when wind or hail did the damage, cash savings, a home equity loan or line of credit, or roof replacement financing arranged through a lender the contractor works with. Most projects mix two of them, like a claim plus the deductible from savings.
Insurance help
Start with insurance when a storm did the damage
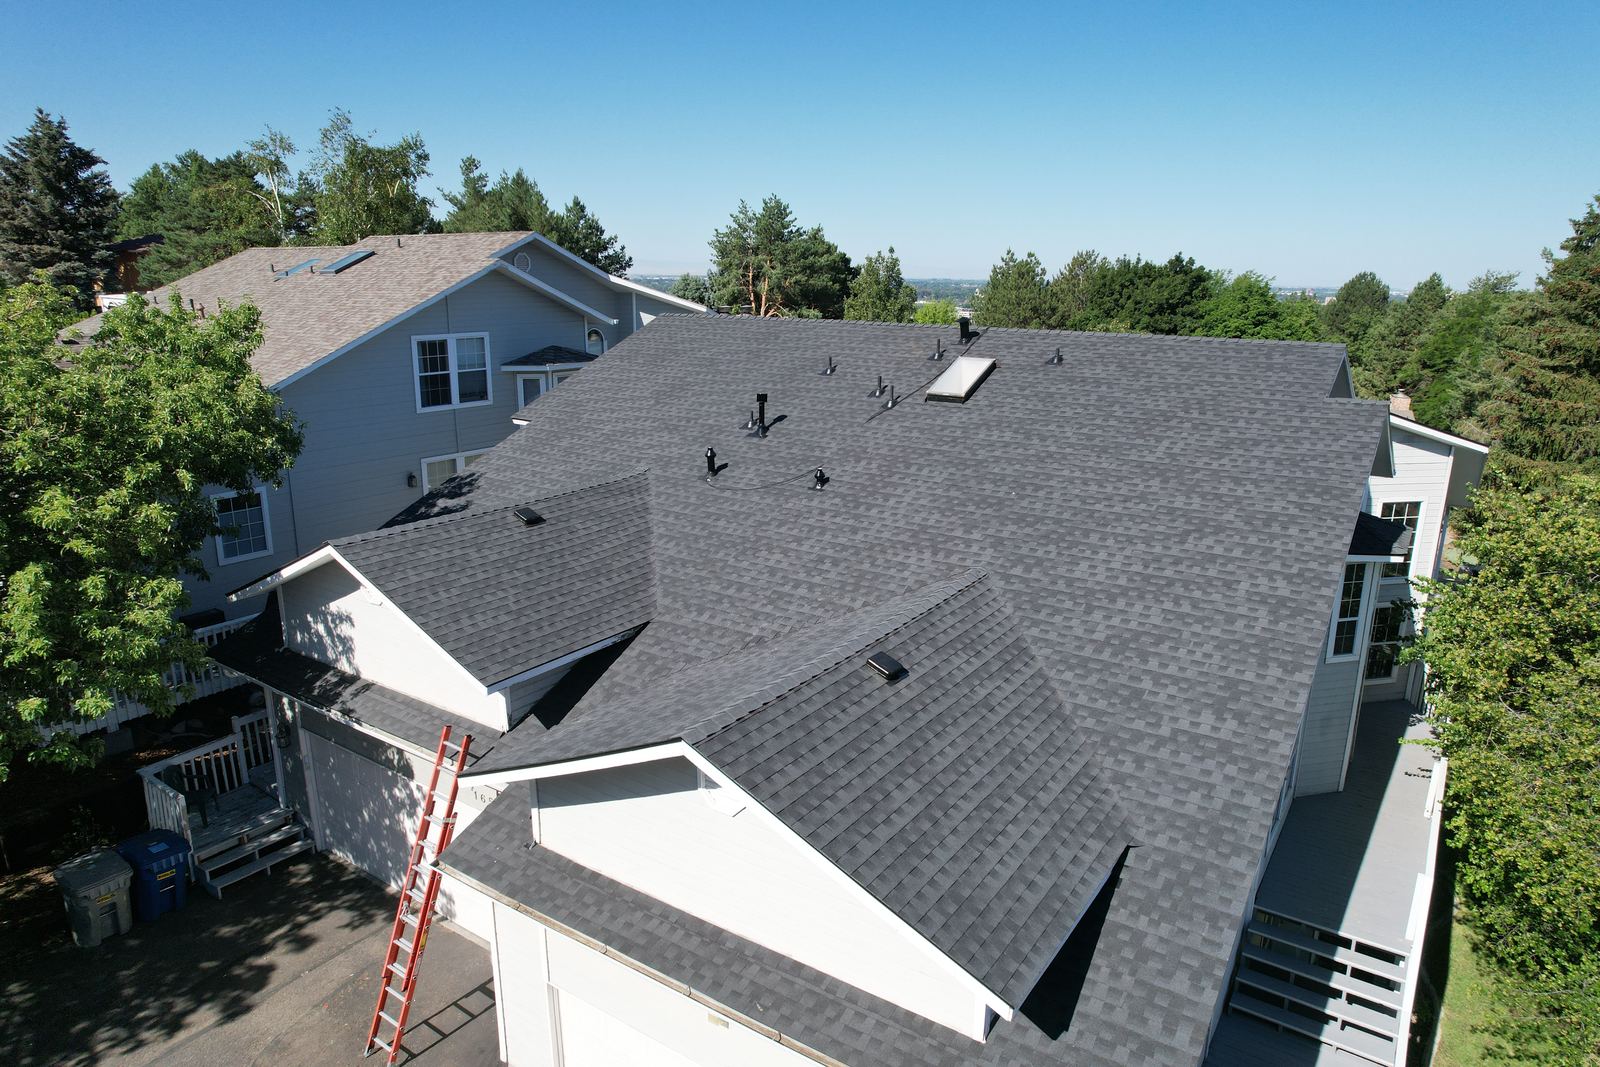
If wind or hail wrecked your shingles, the answer to how to pay for a new roof may be your homeowners policy. The storm damage crew photographs the damage, writes the scope and meets your adjuster, and the insurance claims page walks through the process step by step. The Idaho Department of Insurance publishes plain consumer guidance on home claims, worth reading before you file. Age and wear are not storm damage, so an honest inspection tells you which side of that line your roof sits on. Book one through the free inspection page.
What to know
Savings and home equity
Cash is the cheapest money: no interest, no fees, no loan paperwork. When savings fall short, home equity is the next place many owners look. A home equity loan gives you a lump sum against the value you have built in the house, and a line of credit works more like a card you draw on as bills come due. The Consumer Financial Protection Bureau explains how a home equity loan works and what it costs, and its home ownership guides cover lines of credit and refinancing too. Your bank or credit union can quote real numbers for your situation; a roofer should not.
Detail
Payment plans through a contractor
Plenty of roofing companies that finance do it through an outside lender: the roofer arranges the application, the lender owns the loan. That can be handy, and it can carry costs a cash price does not. Treat it like any other loan. The lender decides approval, rate and term based on your credit, and the roofer has no say in any of it. Before you sign, put the plan next to a home equity quote from your own bank and next to the cash price. Ten minutes of comparison beats years of paying more than you needed to, and a good roofer gives you the time to do the math.
Cost and quotes
What should I ask before taking roof financing?
Ask every lender the same five things and get the answers in writing. What is the full rate, and does it change later? What are the fees, including any charge for paying the loan off early? What happens if a payment lands late? What does the loan cost in total over its life next to the cash price? Who owns the loan after signing?
In practice
The Bork Roofing way to figure it out
We price every roof after an inspection, so your number comes from your roof, not a table. The written estimate spells out the price, and card, cash and check all work. Want to spread the cost out? Ask Bork Roofing about payment options at your estimate and take the paperwork home to read at your own pace. No pressure on the phone, no signature demanded on the first visit. Questions before then? The FAQ page answers the common ones, or reach the office through the contact page: (208) 869-6674, Monday to Friday, 7 AM to 7 PM.
Sources: CFPB on home equity loans · CFPB home ownership guides · Idaho Department of Insurance claims guidance
Questions
Questions homeowners ask
Next step
Get eyes on your roof
A free inspection with photos and a written report, anywhere from Boise to Emmett, from a company that has done this since 2004.